Starting a Coffee Business · 9 of 43
Financing: Loans, Grants and Crowdfunding
Most coffee businesses that start small are paid for out of their own sales, and the ones that borrow mostly borrow for one machine or one lease. The money available to a one-person roaster and stall in Michigan as of October 2026 comes below in order, cheapest first: the business’s own earnings, savings, a 0% Kiva loan, the roaster maker’s own financing, community lenders, SBA and USDA microloans, a bank, a credit card; then the grants that a beekeeper or a downtown shop might qualify for and the ones they will not; then crowdfunding; and finally what a lender wants to see, how the winter months are paid, and a worked example of paying for a production roaster. What each stage of the business costs is on The Numbers; the roasters themselves are compared on Choosing a Roaster.
I sell honey at farmers markets and am saving for a brick-and-mortar store; the coffee stall, the roaster and the shop are plans. Rates and limits below are each lender’s own published terms, read in October 2026. A real offer depends on credit, and any of them can change. Where each kind of money fits on the road to a shop is on Start Here.
The short version
| Source | How much | Cost | Fits |
|---|---|---|---|
| The business’s own sales | One season of bags at one market a week leaves about $2,690 after costs (The Numbers) | Nothing but time | The bag and cup kit (stages 2 and 3 on Start Here); half a roaster a year |
| Savings | What there is | The interest it would have earned | Anything; the safest money |
| Kiva U.S. | $1,000–$15,000; loans on the site in October 2026 include $25,000 for a repeat borrower | 0% interest, no fees, no collateral | A roaster, a cart |
| The roaster maker’s financing | The machine, venting and freight | Mill City Roasters: 0% for 12 months through Navitas Credit, for businesses with good credit and two years’ trading; longer terms at a rate | A production roaster, once the business has two years behind it |
| Michigan Women Forward (community lender) | $2,500–$50,000 | 8%, 3% fee, 3–6 years | Women and entrepreneurs of colour, statewide |
| Northern Initiatives (community lender) | $1,000–$500,000; energy loans $5,000–$75,000 with Michigan Saves | 7–9%, 2–3% fee; energy loans as low as 0% with a utility buydown | Michigan small businesses that banks turn down |
| SBA microloan through a nonprofit lender | Up to $50,000; average about $13,000 | ”Generally between 8%-13%”, up to 7 years | Equipment, stock, working capital; not real estate |
| USDA FSA farm microloan | Up to $50,000 | FSA’s direct rate; up to 7 years for equipment | The bees, not the coffee: hives, bee equipment, a honey house |
| Bank personal loan | Varies | About 11.9% average for a 24-month loan (Federal Reserve, Q2 2026) | Small equipment, with good credit |
| Credit card | The limit | About 22% on balances that pay interest (Fed, Q2 2026) | Only what is paid off within the month |
| SBA 7(a) through a bank | Up to $5 million | Bank rate, capped by SBA rules | A shop: build-out, equipment, a building |
| USDA Value-Added Producer Grant | $75,000 planning, $250,000 working capital (2024 notice) | A grant, matched dollar for dollar | Honey products, possibly. Not coffee. |
| MEDC Match on Main | Up to $25,000, paid after the work | A grant, chosen locally | A shop in a qualifying downtown. Not a stall. |
| Crowdfunding | What supporters give | Platform fees and the rewards | One clear thing: a roaster, a cart, a shop opening |
The order that costs least: sell first, save the season’s profit, borrow at 0% from Kiva for what the season does not cover, and keep credit cards for paying bills on time.
Bootstrapping: let the honey and the bags pay
A market stall can be built in stages, each paid for by the one before, and the costs on The Numbers are small enough that this is realistic.
| Step (Start Here stage) | What it adds | Cost to start | Paid for by |
|---|---|---|---|
| Bags (stage 2) | Bagged coffee, baked goods and jam under cottage food | About $940–$1,150, or $1,420–$1,630 with a learning roaster | The honey sales, and savings |
| Cups (stage 3) | Brewed cups, with a food licence | About $700–$1,000 in kit, plus the licence (about $1,205 the first year for a Transitory Food Unit in Shiawassee County) | The bag sales |
| Roaster (stage 5) | A production roaster | $4,099 (Bullet R2) or $5,299 (R2 Pro), plus venting | Two seasons of bag profit, or a loan |
| Shop (stage 6) | Lease, build-out, espresso, seating | Tens of thousands of dollars or more (Opening a Coffee Shop) | Savings, a loan, possibly a grant |
Stage 1 on Start Here, the market table itself, is the honey stall that already exists; stage 4, a truck, cart or catering, is a branch rather than a step on this road. The Numbers prices the same three steps under its own headings.
The honey business is the head start: the canopy, tables, weights, card reader and the customers are already paid for. One market a week for a 24-week season, selling 18 bags each time at $17, leaves about $2,690 after the cost of the coffee, bags, market fees and samples in the first season, and about $3,490 once green coffee is bought by the box. Two markets a week roughly doubles both. That is a production roaster in two seasons without borrowing, or in one season with a small loan for the rest.
Keep the money apart. A separate business bank account from the first market makes the season’s profit visible, and the account history is the first thing a lender asks for (Setting Up the Business).
Savings and credit cards
Savings cost nothing but the interest they would have earned, carry no payments through the winter when there are no markets, and cannot be called in. The risk is spending money needed for the household; a rule many small owners use is to invest only what could be lost without changing how the household lives.
Credit cards are the most expensive common money. The Federal Reserve’s consumer credit release for the second quarter of 2026 puts the average rate on card accounts that pay interest at 22.15%, against 11.86% for a 24-month personal loan at a commercial bank (Federal Reserve G.19, released 8 September 2026). A $5,299 roaster put on a card at that rate and paid off over three years costs about $7,300, about $2,000 more than its price. A card is a good tool for buying green coffee and supplies and paying the balance in full each month, which builds the business’s credit history at no cost.
“Buy now, pay later” checkout loans (Affirm, Klarna, Shop Pay Installments) appear on many equipment stores. Aillio’s US store runs on Shopify with Shop Pay at checkout; whether instalments are offered on a roaster, and at what rate, shows only at checkout. Treat any such plan as a loan: read the rate and what happens to a late payment.
Kiva U.S.: crowdfunded loans at 0%
Kiva U.S. lends to US small businesses at “0% interest … with no fees, no collateral”, using money from individual lenders on its website. How it works, in Kiva’s own steps:
- Apply online (30–60 minutes); approval takes 20–25 business days.
- Private fundraising: the borrower proves creditworthiness “by inviting friends, family, and others to lend” (usually 10–15 days).
- Public fundraising on Kiva’s site, to “over 2 million lenders” (usually 20–30 days).
- Repay monthly, starting one month after receiving the loan, usually over 12–36 months.
Eligibility includes being 18 or over, living and operating in the US (not Nevada or North Dakota), not being in foreclosure or bankruptcy, using the loan for business rather than refinancing, and having a PayPal account, through which the loan is paid out and repaid. Loans being raised on the site in October 2026 were mostly $8,000 to $15,000, with $25,000 for a borrower on a second loan. One of them was a Chicago coffee company raising $25,000 for equipment.
For a market roaster Kiva fits unusually well: the amount matches a roaster, the private round is the stall’s own regulars, and a loan page with a photo and the story is marketing in its own right (Marketing on a Shoestring). The cost is the time to raise it and the public nature of it.
The roaster maker’s own financing
Roaster makers and dealers sell on credit, because a production roaster is a large purchase for a small business. Mill City Roasters, which makes and sells shop roasters in Minneapolis, advertises “0% interest for 12 months” through Navitas Credit, with longer terms of 18 to 60 months “at competitive rates.” Its terms, read in October 2026:
- Who qualifies: “well-qualified businesses & owners in the US”; businesses with good credit “and at least two years in business typically qualify quickly.” A first-year stall usually does not.
- What it covers: the roaster, venting, accessories and freight can be put on one agreement.
- Credit check: a soft inquiry, which does not mark a personal credit report; the loan is the business’s.
- The catch: the 0% lasts 12 months. A $19,500 shop roaster at 0% over 12 months is $1,625 a month, more than a small business clears in a winter; the longer terms carry interest, and the page says there is no benefit to paying off early.
Restaurant-equipment dealers finance espresso machines, brewers and refrigeration on similar terms. Any of these can beat a community lender if the business qualifies and can pay inside the 0% period; read the rate that applies after it, and whether interest is charged back to the start if the balance is not cleared in time.
Community lenders (CDFIs) in Michigan
A community development financial institution (CDFI) is a lender, usually nonprofit, certified by the US Treasury to lend where banks do not. Their rates are higher than a bank’s best and lower than a card’s, and most include coaching.
| Lender | Loans | Terms | Who | Notes |
|---|---|---|---|---|
| Michigan Women Forward | $2,500–$50,000 microloans | 8% interest; 3% fee at closing; no prepayment penalty; repaid over 3–6 years | Its mission is “to expand economic opportunity for women and entrepreneurs of color” across Michigan | Can be used for start-up costs, inventory, equipment, marketing, rent, payroll; not real estate or repaying other loans |
| Northern Initiatives (Marquette; statewide) | $1,000–$500,000 | 7–9% fixed or variable; 2–3% origination fee | ”New entrepreneurs”, businesses in underserved communities, healthy food businesses | ”We say yes when banks can’t”; looks at “character and cash flow”; free online coaching portal |
Northern Initiatives and Michigan Saves. Its home page announces that it “is now part of Michigan Saves”; its loans page puts it more exactly: it “is one of only three commercial lenders working with the statewide nonprofit green bank, Michigan Saves.” It is a lending partner, not a branch. Through that programme it makes energy-efficiency loans of $5,000 to $75,000, and “the interest rate can be as low as 0% when borrowers utilize an interest rate buydown program available through some of Michigan’s utilities.” Whether an electric roaster, an afterburner, a heat-pump water heater or LED lighting in a shop counts as an eligible energy upgrade is a question for Michigan Saves and the utility; for a shop build-out it is worth asking before borrowing at 9%.
The SBA’s list of microloan intermediaries shows which nonprofit lenders serve Michigan with SBA money; filter it by state. The Michigan SBDC knows the local lenders and helps with the application at no cost.
SBA loans
The US Small Business Administration does not usually lend directly; it funds or guarantees loans made by others.
| SBA microloan | SBA 7(a) | |
|---|---|---|
| Through | A nonprofit intermediary lender | A bank or credit union |
| Amount | Up to $50,000; average about $13,000 | Up to $5 million |
| Rate | Set by the intermediary, “generally between 8%-13%“ | Set by the lender, within SBA maximums |
| Term | Up to 7 years | Varies by use; equipment and real estate longer |
| Use | Working capital, inventory, supplies, furniture, fixtures, machinery, equipment. Not existing debts or real estate. | Real estate, buildings, equipment, working capital, buying a business |
| Fits | A roaster, a cart, a stall’s first year | A shop |
Sources: SBA, Microloans and 7(a) loans, October 2026.
Banks making 7(a) loans for a shop commonly ask for a business plan, the business’s tax returns or a strong personal financial record, some of the owner’s own money in the project, and a personal guarantee. A few seasons of a stall’s sales records are exactly the history that makes one possible. SBA’s Lender Match service connects a borrower with SBA lenders.
USDA farm microloans: for the bees
The USDA’s Farm Service Agency makes microloans of up to $50,000 (7 CFR 761.2) for “small, beginning farmer, niche and non-traditional farm operations,” including “farms participating in direct marketing and sales such as farmers’ markets.” Its list of what an operating microloan can buy includes “Bees and bee equipment”, beside hoop houses and a “Maple sugar shack.” Equipment and livestock loans run up to seven years; annual operating costs are repaid within twelve months or when the crop sells.
That makes it a route for the honey side: more hives, extracting equipment, a honey house. It does not pay for a coffee roaster, because coffee is not something the farm produces, and the FSA excludes businesses that primarily market goods “not produced by the farming operation.” The local FSA county office says whether a particular apiary qualifies and what the current rate is. Money the honey side does not have to find is money the coffee side can keep.
Grants: which ones fit, and which do not
Grants for starting a small food business are fewer than the internet suggests, and most have conditions that rule out a coffee roaster. Two are worth knowing in detail because one might fit the honey and the other a future shop.
USDA Value-Added Producer Grant: the honey, not the coffee
The Value-Added Producer Grant (VAPG) helps farmers turn what they grow into a product worth more. The rule that decides it: the applicant must “produce and own more than 50 percent of the Agricultural Commodity to which value will be added”, and keep ownership “from its raw state through the production and marketing” of the product (7 CFR 4284.920).
- Coffee does not qualify. A Michigan roaster buys green coffee grown abroad; it produces none of it.
- Honey may. A beekeeper produces the honey, so a project to make and market a honey product (flavoured honey, creamed honey, honey for coffee) is the kind of thing the programme exists for. Whether a particular project qualifies is for USDA Rural Development’s Michigan state office to say.
| Fiscal year 2024 notice | |
|---|---|
| Maximum planning grant | $75,000 |
| Maximum working-capital grant | $250,000 |
| Match | ”at least $1 for every $1 in grant funds”, in cash or eligible in-kind contributions; the applicant’s own honey inventory can count |
| Period | Up to 36 months |
| Deadline | 11 April 2024 (electronic) |
Source: Federal Register, 17 January 2024. Each year’s amounts and deadline are set in that year’s notice; check the current one. The application is long (a registration on SAM.gov, a work plan, a budget, a feasibility study for working-capital grants), and the matching dollar must be in hand at the time of application. It suits a honey business that has outgrown a market table more than one starting out.
MEDC Match on Main: a shop downtown, not a stall
Match on Main is a Michigan Economic Development Corporation grant of up to $25,000 per project for “new and expanding place-based small businesses” in downtowns. The conditions, from MEDC’s page:
- The business does not apply. A local government, downtown development authority or Main Street organization applies on the business’s behalf, and may put forward up to two businesses a round.
- Only certain towns. The community must be a Redevelopment Ready Community (Essentials or Certified) or a Michigan Main Street community at Select or Master level.
- Reimbursement only. The money is paid after the project is “fully completed”, in one lump sum; “Advance, partial, or milestone-based payments are not permitted.” The business must be able to pay for the work first.
- Place-based. It is for a physical business in a commercial district: a market stall, a cart or an online shop does not fit.
- Timing. The 2026 round’s application window was 1 March to 24 April 2026.
For a future coffee shop it is worth a conversation with the downtown development authority or Main Street manager of the town where the shop might go, before signing a lease. MEDC reports that funded businesses raised their annual revenue by an average of $58,200.
Grant warnings
- Nobody charges a fee to get a government grant. Offers of “guaranteed” small-business grants for a fee are scams.
- Pitch competitions (Michigan Women Forward runs one) and local foundation grants exist and are small; the SBDC and the chamber of commerce know the local ones.
Crowdfunding
| Kind | How it works | Platforms | Fits |
|---|---|---|---|
| Rewards | Supporters pay in advance for rewards: bags of coffee, a subscription, a mug, a tasting. | Kickstarter (all-or-nothing: “No one will be charged for a pledge towards a project unless it reaches its funding goal”), Indiegogo | A roaster, a cart, a shop’s opening. The rewards are coffee the stall must then roast and ship. |
| Loan crowdfunding | Supporters lend; the business repays. | Kiva U.S. (0% to the borrower) | Covered above |
| Investment crowdfunding | Supporters buy a share of revenue, a loan note or equity, under the SEC’s Regulation Crowdfunding. | Honeycomb Credit (local-business loans; “500+” businesses funded); others | A shop with a lease and a plan |
Regulation Crowdfunding lets a company raise up to $5 million in 12 months from the public, only through an SEC-registered funding portal or broker, with disclosure filings and limits on what each investor may put in (SEC). It is far more paperwork than a stall needs, and the platforms take fees. One platform that many small cafés used for revenue-sharing offerings, Mainvest, is gone: its web address no longer resolves as of October 2026.
Rewards crowdfunding, done for a roaster, looks like this: a goal equal to the roaster’s price plus the platform’s fees and the cost of the rewards; rewards that are mostly coffee already planned (a bag a month for three months, a first-roast bag with the date, a tasting for four); and a campaign launched to the email list built at the market. A campaign that asks strangers for money without a list behind it usually fails; one that asks a stall’s regulars to pre-pay for coffee usually does not need strangers.
What a lender wants to see
Every lender above, from Kiva to a bank, asks for some version of the same things.
| Item | What it is | Where to start |
|---|---|---|
| A business plan | Two to ten pages: what is sold, to whom, where, at what price, what it costs, and what the money is for | The Plan and the SBDC’s free help |
| The numbers | Costs per bag and per cup, a season’s sales, a cash-flow forecast month by month through the winter | The Numbers |
| Sales records | A season or more of dated market sales, from the card reader’s reports and a cash tally | Taking Cards, Setting Up the Business |
| Licences and registrations | The assumed name, any food licence, sales tax licence, EIN | Setting Up the Business, The Michigan Rules |
| Insurance | Proof of liability cover | Insurance |
| A quote | The maker’s price page or written quote for what the money buys | The roaster’s own store |
| Personal credit | A credit report; most small-business loans are personally guaranteed | Free reports at annualcreditreport.com |
| Owner’s money in | Most lenders want the owner to put in some of the cost | The season’s savings |
The winter is the line lenders read most closely. A stall earns from May to October; a loan payment is due every month. A cash-flow forecast that shows how the January and February payments are made is the difference between a plan and a hope.
Paying through the winter
A worksheet for the simplest case: one market a week, a 24-week season from May to October, the first season’s $2,690 of bag profit spread evenly over six months (about $448 a month), and the Kiva loan for the R2 Pro at $147.19 a month. The rule is to put one month’s payment aside for every month of market, so the winter is paid from the summer.
| Month | Left after costs | Loan payment | Into (or out of) the winter reserve | Reserve at month end | Left for the business |
|---|---|---|---|---|---|
| May–October, each | $448 | $147 | +$147 | $147, rising to $883 | $154 |
| November–April, each | $0 | $147 | −$147 | $736, falling to $0 | $0 |
| Year | $2,690 | $1,766 | $924 |
Three things the worksheet shows:
- Six winter payments are $883. That is the sum to have in the reserve on the last market day. A season that falls short of it is visible by August, while there is still time to add a market.
- A loan raised in winter starts before the markets. Kiva repayments begin a month after the money arrives. A loan funded in January means payments in February, March and April with no market income at all, paid from savings; time the loan, or the reserve, for it.
- Holiday sales help. Gift boxes in November and December and pre-orders over the winter (Gift Baskets; Selling Online and by Mail) are the only winter income a market business has, and they go first to the reserve.
The same table with the real season’s sales month by month, not an even average, is the cash-flow forecast a lender asks for. Market sales are not even: spring is slow and late summer is busy, so the reserve fills late.
Worked example: an Aillio Bullet R2 Pro
The Bullet R2 Pro cost $5,299 on Aillio’s US store in October 2026, with free shipping. It runs on 240 V, so the cost of a circuit and of venting comes on top; both depend on the building (Choosing a Roaster, Smoke, Air Permits and the Neighbours). The roaster alone, paid over 36 months:
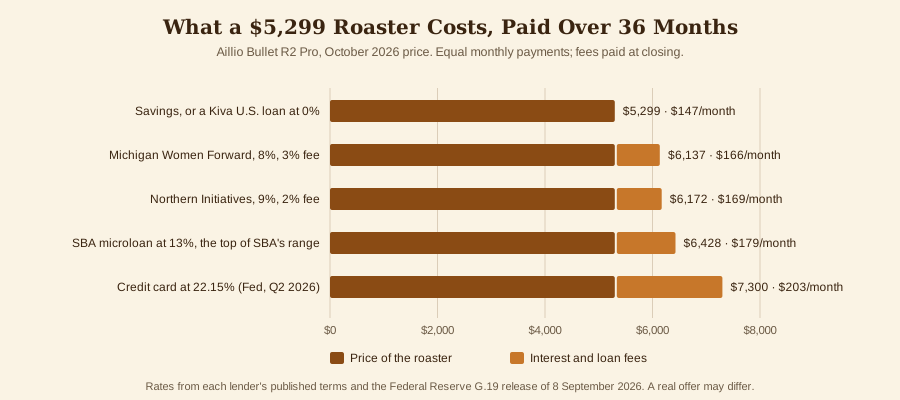
| Route | Monthly | Total paid | Extra over the price |
|---|---|---|---|
| Two seasons’ savings | — | $5,299 | $0 |
| Kiva U.S., 0%, 36 months | $147.19 | $5,299 | $0 |
| Michigan Women Forward, 8%, 36 months, 3% fee | $166.05 | $6,137 | $838 |
| Northern Initiatives, 9%, 36 months, 2% fee | $168.51 | $6,172 | $873 |
| SBA microloan, 13%, 36 months | $178.54 | $6,428 | $1,129 |
| Credit card, 22.15%, 36 months | $202.78 | $7,300 | $2,001 |
Against the season. At one market a week, the season’s bag profit of about $2,690 has to cover twelve payments: about $1,770 a year at Kiva, $2,000 at 8%, $2,430 on a card. The card route takes nine-tenths of a season’s bag profit for three years. At two markets a week, or once the brewed cups are added (a cup earns several times what a bag does per pound of coffee, The Numbers), any of the loans is comfortable.
Against the roaster’s own payback. Each bag sold leaves $8.61 after its making cost and a card fee in the first season, so the R2 Pro is paid for by about 615 bags (461 lb of roasted coffee), and by about 512 once green is bought by the box (The Numbers). At 18 bags a market that is about 34 markets: a little under a season and a half at one market a week, or most of one season at two.
A sensible plan for this roaster. Save the first season’s bag profit; raise the rest as a Kiva loan in the winter, with the private round going to the market’s regular customers; roast on it from the spring. Total interest: nothing. The weak point is the first season’s learning roaster: Behmor voids the warranty for commercial use (Choosing a Roaster), so a stall may choose to buy a few months of toll roasting or shared-roastery time instead.
Questions to ask any lender
- What is the interest rate, and is it fixed or variable?
- What fees are charged at closing, and are they taken out of the loan?
- Is there a penalty for paying early?
- Is a personal guarantee or collateral required?
- Can payments be lower or paused in the winter months? (Some community lenders offer seasonal schedules; ask.)
- What happens if a payment is late?
- Is coaching or technical help included?
- How long from application to money in the account?
What is not known
- Whether any Michigan community lender offers seasonal (summer-heavy) repayment schedules as a standard product; none publishes one, so it is a question to ask.
- Kiva’s borrower page gives $1,000 to $15,000; how often it lends more to repeat borrowers is not stated, beyond the $25,000 loans listed there in October 2026.
- Whether a roaster or shop equipment counts as an energy upgrade for a Michigan Saves loan; ask.
- The Value-Added Producer Grant amounts for the current year are set in a notice that had not appeared in the Federal Register after the 2024 one; the program office has the current figures.
- Whether a USDA reviewer would treat honey sold to sweeten the stall’s own coffee as a value-added honey product is not settled by the regulation.
Sources
- US Small Business Administration: Microloans; List of microlenders; 7(a) loans.
- Michigan Women Forward, our loan options and home page.
- Northern Initiatives, available loans and energy-efficiency financing; Michigan Saves.
- Mill City Roasters, coffee roaster financing (Navitas Credit), read 6 October 2026.
- USDA Farm Service Agency, Microloans (archived copy); 7 CFR 761.2 (microloan of $50,000 or less; non-eligible enterprise).
- Kiva U.S., apply for a loan.
- USDA Value-Added Producer Grants: 7 CFR part 4284, subpart J; Fiscal year 2024 notice of funding opportunity, Federal Register, 17 January 2024.
- Michigan Economic Development Corporation, Match on Main.
- Securities and Exchange Commission, Regulation Crowdfunding.
- Honeycomb Credit.
- Kickstarter, What are the fees? (all-or-nothing funding).
- Federal Reserve, Consumer Credit G.19, released 8 September 2026.
- Aillio, Bullet R2 Pro.
- Michigan Small Business Development Center.
- On this site: The Numbers, Choosing a Roaster, Setting Up the Business, The Plan, Insurance.
Comments (0)